ether.fi Cash Explained: How 3% Cashback, Membership and Borrow Mode Work
How ether.fi Cash's 3% cashback steps down by Membership level and monthly spend, what Luxe and Pinnacle cost, and how Direct Pay differs from Borrow Mode.
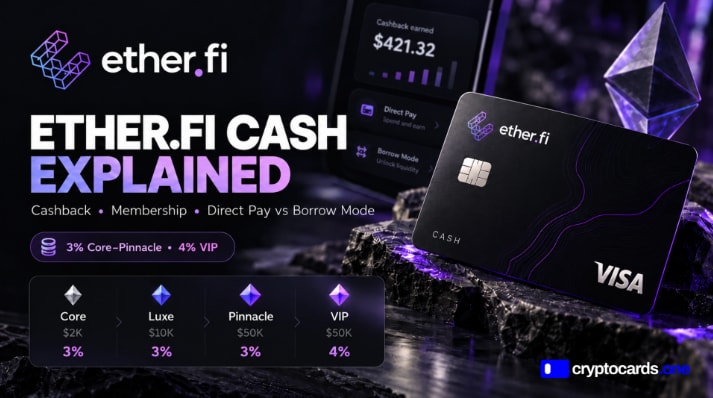
CryptoCards.one graphic titled "ether.fi Cash Explained", showing the black ether.fi Cash Visa card and the four Membership levels: Core, Luxe, Pinnacle and VIP
ether.fi Cash combines crypto-backed spending, cashback and onchain borrowing in one Visa card product.
The headline 3% cashback rate is a useful starting point, but the actual economics depend on Membership level, monthly spending, transaction currency and whether purchases are funded directly or through Borrow Mode.
CryptoCards.one reviewed ether.fi's current documentation and contacted the team directly to clarify the cashback and Membership mechanics.
Cashback is progressive
ether.fi does not simply stop paying cashback once a monthly threshold is reached. Instead, the rate steps down progressively as eligible spending increases.
For USD purchases:
Core
- 3% on the first $2,000 per month
- 1% on the next $1,000
- 0.5% above $3,000
Luxe
- 3% on the first $10,000
- 1% on the next $10,000
- 0.5% above $20,000
Pinnacle
- 3% on the first $50,000
- 1% on the next $30,000
- 0.5% above $80,000
VIP
- 4% on the first $50,000
- 2% on the next $30,000
- 1% above $80,000
ether.fi confirmed to CryptoCards.one that this progressive structure has been in effect for several months.
These are progressive bands. Crossing a threshold does not retroactively reduce the cashback earned on earlier spending.
What the headline rate means in practice
Because the rates step down, the effective cashback rate across a full month can be lower than the headline tier rate.
Take a Core user spending $5,000 on eligible USD purchases:
- First $2,000 at 3% = $60
- Next $1,000 at 1% = $10
- Remaining $2,000 at 0.5% = $10
Total cashback is $80, equivalent to an effective rate of 1.6% across the full $5,000.
Higher Membership levels extend the amount of spending receiving the higher rate. At $15,000 of eligible USD spending in a month, CryptoCards.one calculates:
- Core: $130, or 0.87%
- Luxe: $350, or 2.33%
- Pinnacle: $450, or 3%
- VIP: $600, or 4%
These examples exclude other Membership benefits, FX effects and movements in the value of ETHFI after conversion.
The practical question is therefore not only what cashback percentage a card offers, but how much of a user's normal monthly spending actually receives that percentage.
Cashback is paid in ETHFI
ether.fi currently pays Cash cashback in ETHFI rather than fiat or a stablecoin.
Cashback is initially calculated in dollar terms. Once an eligible card transaction clears, the reward is converted into ETHFI at the current price and enters a seven-day lock period.
After the lock, the ETHFI becomes claimable. Users need at least $5 of claimable cashback before making a claim.
This means the eventual dollar value of the reward can move with the price of ETHFI after conversion. For users comparing cards purely on predictable fiat-equivalent cashback, the payout asset is therefore worth considering.
Membership determines how far the higher rate goes
ether.fi currently has four personal Membership levels: Core, Luxe, Pinnacle and VIP.
Core is free. Luxe and Pinnacle can be reached through monthly Membership points, eligible Liquid balances, ETHFI staking or an annual paid upgrade.
Luxe
- 5,000 monthly Membership points
- or $15,000 Liquid Deposit
- or 30,000 ETHFI staked
- or $199 per year
Pinnacle
- 25,000 monthly Membership points
- or $100,000 Liquid Deposit
- or 150,000 ETHFI staked
- or $999 per year
VIP
- $500,000 Liquid Deposit
- or 500,000 ETHFI staked
The 5,000 and 25,000-point figures are monthly qualification thresholds, not lifetime accumulated totals. Annual Membership purchases and balance or staking qualification are separate routes.
No token staking is required to earn Core's base cashback rate.
For users considering a paid tier primarily for rewards, there is also a breakeven calculation.
Based purely on the current USD base cashback ladders, CryptoCards.one calculates that a Core user spending around $2,830 of eligible purchases each month would earn enough additional base cashback at Luxe to offset the $199 annual Membership cost over 12 months.
For someone comparing paid Luxe with paid Pinnacle, the additional $800 annual cost is recovered through base cashback at roughly $13,330 of eligible USD spending per month.
Those calculations exclude other Membership benefits and should not be treated as a complete valuation of either tier.
EUR spending uses different thresholds
EUR purchases have their own cashback ladder, with all thresholds measured in USD-equivalent spending.
Core
- 3% up to $800
- 1% from $801 to $1,500
- 0.1% above $1,500
Luxe
- 3% up to $3,000
- 1% from $3,001 to $6,000
- 0.1% above $6,000
Pinnacle
- 3% up to $16,000
- 1% from $16,001 to $26,000
- 0.1% above $26,000
VIP
- 4% up to $16,000
- 2% from $16,001 to $26,000
- 0.1% above $26,000
USD and EUR purchases share one monthly spending counter, but each purchase uses the cashback ladder applicable to its own currency.
EUR purchases currently receive 0% ether.fi FX markup.
For transactions in currencies other than USD or EUR, FX rates can apply. Where conversion is required, ether.fi applies the prevailing FX base rate and may add a tier-dependent margin:
- Core: 0% to 0.5%
- Luxe: 0% to 0.25%
- Pinnacle: no additional tier margin
- VIP: no additional tier margin
For international users, cashback and FX therefore need to be considered together.
Direct Pay vs Borrow Mode
The other defining feature of ether.fi Cash is how purchases can be funded.
Direct Pay currently draws directly from USDC and LiquidUSD balances. Purchases are deducted from those supported assets without creating a card loan or generating borrowing interest.
Borrow Mode works differently. Card purchases automatically borrow against the collateral value of supported assets rather than selling or directly spending them.
Supported collateral can include crypto, tokenized equities, gold, ETFs and other eligible assets. This allows users to retain exposure to assets while accessing spending power, and eligible collateral can continue generating yield while supporting a loan.
Borrow Mode, however, is still a form of borrowing, so users need to account for interest and collateral risk.
ether.fi says borrowing rates are variable and depend on the underlying lending market, with rates currently starting at approximately 1% depending on collateral and market conditions. Interest accrues while the borrowing remains outstanding.
Borrowing against assets also introduces liquidation risk if market movements push the position to its applicable liquidation threshold.
A 3% cashback reward on a Borrow Mode purchase should therefore not automatically be treated as a 3% net return. The result also depends on borrowing costs, how long the loan remains open, collateral yield and movements in the value of the collateral.
For users who deliberately want to retain their portfolio while accessing liquidity, Borrow Mode is one of ether.fi Cash's more distinctive features.
For users who simply want to spend supported balances without creating debt, Direct Pay is the more straightforward option.
Availability and card access
ether.fi says Cash is currently available to eligible members in 90 countries and territories, plus 31 supported U.S. jurisdictions.
Availability remains subject to identity verification, compliance requirements and card-programme eligibility, while physical-card availability varies by location.
Cash runs on Visa and is available in virtual and physical formats. Eligible virtual cards can be provisioned to supported Apple Pay and Google Pay devices.
The current Core physical card costs $60 including standard shipping, while higher Membership tiers include a physical card as part of their benefits.
ether.fi says Cash now has more than 100,000 cardholders.
CryptoCards.one view
ether.fi Cash is more than a straightforward cashback card.
Core provides 3% on the first $2,000 of eligible monthly USD spending without requiring a paid Membership. Luxe and Pinnacle substantially extend the 3% range, while VIP starts at 4% and retains stronger rewards at higher spending levels.
Direct Pay offers relatively straightforward spending from supported stable balances. Borrow Mode serves a different purpose, allowing users to retain exposure to supported assets while borrowing against them.
That flexibility can be valuable for users actively managing an onchain portfolio, but it also introduces borrowing costs and collateral risk that do not exist with direct-funded spending.
For anyone comparing ether.fi Cash with another crypto card, three questions matter most: how much eligible spending do you normally put through a card each month, which Membership level can you realistically qualify for or justify paying for, and do you want to spend existing balances directly or borrow against assets you intend to keep?
Those answers provide a much clearer picture of ether.fi Cash than the headline cashback percentage alone.
More on this card: our ether.fi Cash review, Gemini vs ether.fi Cash and our earlier report on card spending earning fewer Membership points.
Sources: ether.fi Help Center, How does cashback work?, Why is my cashback locked and when can I claim it?, Membership level benefits, How do Membership levels work?, EUR purchases 0% FX Rate, What's the foreign exchange (FX) rate used on Cash transactions?, Understanding your Cash card: Borrow Mode vs Direct Pay Mode and In which countries is the Cash card available?, read on 8 October 2026; and ether.fi's responses to CryptoCards.one.
Common questions
Does ether.fi Cash stop paying cashback after the monthly threshold?
No. The rate steps down progressively as eligible spending increases. On USD purchases, Core earns 3% on the first $2,000 per month, 1% on the next $1,000 and 0.5% above $3,000. Crossing a threshold does not retroactively reduce the cashback earned on earlier spending.
How is ether.fi Cash cashback paid?
In ETHFI rather than fiat or a stablecoin. Cashback is initially calculated in dollar terms. Once an eligible card transaction clears, it is converted into ETHFI at the current price and enters a seven-day lock period. After the lock it becomes claimable, and users need at least $5 of claimable cashback before making a claim.
When does paying $199 a year for ether.fi Luxe pay for itself?
Based purely on the current USD base cashback ladders, CryptoCards.one calculates that a Core user spending around $2,830 of eligible purchases each month would earn enough additional base cashback at Luxe to offset the $199 annual Membership cost over 12 months. That excludes other Membership benefits.
What is the difference between Direct Pay and Borrow Mode?
Direct Pay draws directly from USDC and LiquidUSD balances, without creating a card loan or generating borrowing interest. In Borrow Mode, card purchases automatically borrow against the collateral value of supported assets rather than selling or spending them, so interest accrues while the borrowing remains outstanding and there is liquidation risk.
Cards mentioned in this article
Card figures referenced here come from each issuer's published terms and each card page shows when its data was last verified — see our methodology for how, and the changelog for what has changed since. Rewards and availability vary by region and move often. Not financial advice.